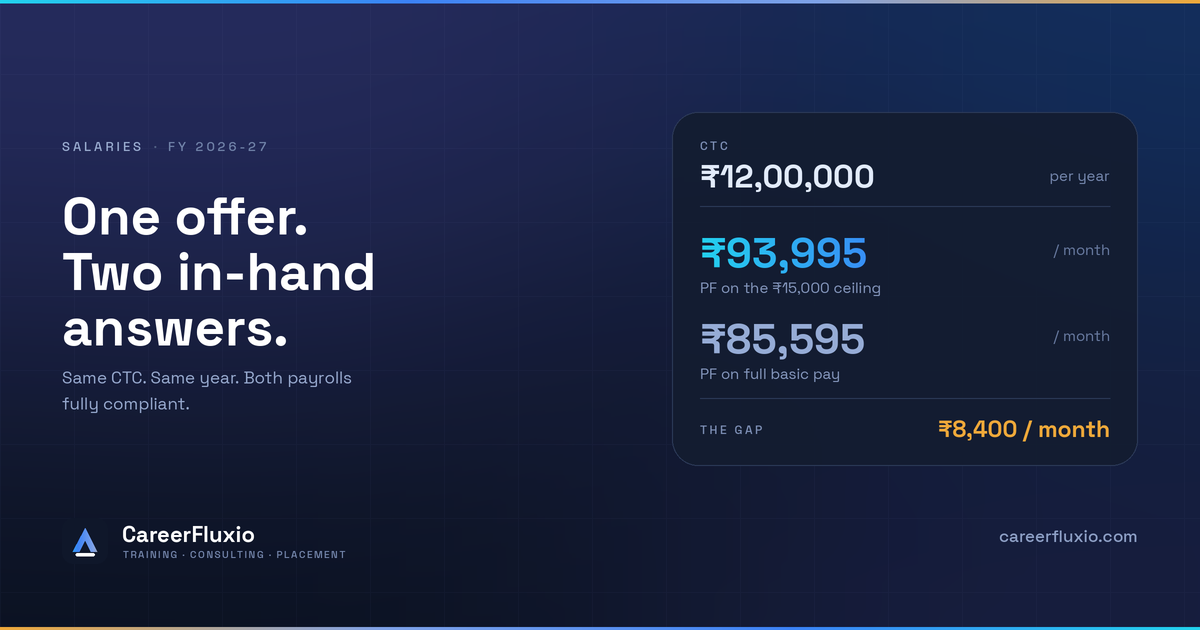
Two people can hold the same ₹12,00,000 offer letter, work at compliant companies, and take home amounts that differ by ₹8,400 every month. After the labour codes and the new provident fund scheme, that gap is legal and mostly invisible until your first payslip.
The short answer: a ₹12,00,000 CTC pays roughly ₹93,995 a month if your employer deducts provident fund only on the ₹15,000 statutory wage ceiling, and roughly ₹85,595 a month if it deducts on your full basic pay. Income tax at this level is nil under the new regime. The ₹1,00,000 a month you get by dividing ₹12 lakh by twelve has never existed for anyone.
Three things that changed in 2026
If you are using a take-home calculator that predates November 2025, it is giving you the wrong number. Three separate changes landed inside nine months, and all three touch the line between CTC and in-hand.
- The four labour codes came into force on 21 November 2025, replacing 29 older central labour laws. The central rules that make them operational were notified on 8 May 2026. States are still notifying their own rules at different speeds, which is why your Bengaluru colleague's structure may already look different from yours in Noida.
- A single definition of "wages" now applies across statutes. Excluded components such as house rent allowance and conveyance cannot exceed half of your total remuneration. If they do, the excess is pulled back into wages for statutory calculations. In practice this pushes basic pay to at least 50% of CTC.
- The Employees' Provident Fund Scheme, 2026 took effect on 29 June 2026, replacing the 1952 scheme. It states plainly that the mandatory employee contribution is 12% of the ₹15,000 statutory wage ceiling ₹1,800 a month and that anything above that is voluntary.
Income tax, for once, is the stable part. The slabs under the new regime are unchanged for FY 2026-27, the standard deduction stays at ₹75,000, and the rebate under section 87A still takes tax to nil where taxable income does not cross ₹12,00,000. The Income Tax Act, 2025 has replaced the 1961 Act for this tax year, but the arithmetic a salaried employee faces has not moved.
Five parts of CTC that never reach your bank account
CTC is a budgeting number invented by employers. It answers "what does this person cost us", not "what will this person be paid". Five components routinely sit inside it and never appear in your account:
- The employer's provident fund contribution. Real money, legally yours, locked until you withdraw it. Not spendable this month.
- A gratuity provision, usually 4.81% of basic. You forfeit it entirely if you leave before five years of continuous service. Fixed-term employees are the exception under the Code on Social Security they earn it pro-rata after one year.
- Insurance premiums for group medical, accident and term cover. A genuine benefit, counted at cost, worth nothing in cash.
- Conditional and one-time pay: joining bonus, retention bonus, performance-linked variable. Variable pay is quoted at 100% and rarely paid at 100%.
- Notional ESOP value, in startups. A number on a slide until there is a liquidity event.
Ask for the gross monthly figure, not the annual CTC. Gross is the only number in an offer letter that behaves the way you expect it to.
The full arithmetic on a ₹12 LPA offer
Here is a compliant structure on ₹12,00,000, with basic at 50% of CTC, and the two provident fund treatments side by side. Everything below assumes the new tax regime, no professional tax, and no variable component.
| Component | PF on ₹15,000 ceiling | PF on full basic |
|---|---|---|
| Basic pay (50% of CTC) | ₹6,00,000 | ₹6,00,000 |
| HRA | ₹3,00,000 | ₹3,00,000 |
| Special allowance | ₹2,49,540 | ₹1,99,140 |
| Less: employer PF (in CTC, not paid to you) | −₹21,600 | −₹72,000 |
| Less: gratuity provision (4.81% of basic) | −₹28,860 | −₹28,860 |
| Gross salary | ₹11,49,540 | ₹10,99,140 |
| Less: employee PF | −₹21,600 | −₹72,000 |
| Less: income tax (nil after ₹75,000 standard deduction and 87A rebate) | ₹0 | ₹0 |
| In-hand per month | ₹93,995 | ₹85,595 |
Rounded to the nearest rupee. Add professional tax where your state levies it, and subtract your variable component if part of the CTC is performance-linked.
Two things are worth noticing. First, neither column is anywhere near ₹1,00,000; the shortfall is between ₹6,000 and ₹14,400 a month, and none of it is a deduction anyone hid from you. Second, the ₹8,400 monthly gap between the columns is not a difference in generosity. It is a difference in where the same rupees are parked.
The same maths from ₹6 LPA to ₹36 LPA
CTC CTC ÷ 12 PF on ceiling PF on full basic Annual tax
₹6,00,000 ₹50,000 ₹45,198 ₹42,798 Nil
₹9,00,000 ₹75,000 ₹69,596 ₹64,196 Nil
₹12,00,000 ₹1,00,000 ₹93,995 ₹85,595 Nil
₹18,00,000 ₹1,50,000 ₹1,31,351 ₹1,18,334 ₹1,29,209
₹24,00,000 ₹2,00,000 ₹1,68,934 ₹1,51,186 ₹2,71,877
₹36,00,000 ₹3,00,000 ₹2,36,748 ₹2,09,402 ₹5,66,265
The pattern holds across the ladder, and the gap between the two provident fund treatments widens as basic pay rises.
Tax shown for the PF-on-ceiling column. Assumes basic at 50% of CTC, gratuity provision at 4.81% of basic, no professional tax, no variable pay, no old-regime deductions.
The useful rule of thumb: below ₹12.75 lakh of gross salary you lose roughly 8–10% of CTC to provident fund and gratuity and nothing to tax. Above it, the tax wedge grows quickly at ₹36 lakh you are keeping about 79% of CTC as cash, and that is before the pay-cheque even meets your rent.
What the 50% wage rule does to your payslip
For years Indian payroll design worked in one direction: keep basic pay low, inflate allowances, and shrink every wage-linked liability at once. Provident fund, gratuity, bonus and leave encashment all key off "wages", so a basic of 25–30% of CTC was cheap for the employer and cash-rich for the employee.
The Code on Wages closes that door by capping excluded allowances at half of total remuneration. If your allowances run higher, the excess is treated as wages anyway. The effects, in order of how quickly you will feel them:
- Gratuity rises, because it is 15 days' wages for each completed year of service and wages just went up.
- Notice-period pay, leave encashment and retrenchment compensation rise for the same reason. This matters more than people expect during a resignation or a layoff.
- Bonus and employee state insurance eligibility shift, bringing some employees into coverage who were previously outside it.
- Provident fund is the messy one. The broader wage definition and the ₹15,000 ceiling pull in opposite directions, and payroll teams are still settling on a consistent treatment. This is exactly why two compliant employers can hand you different net figures.
What this is not: it is not a pay cut, and your CTC does not change. Money moves from monthly cash into deferred and statutory benefits. Whether that is welcome depends entirely on whether you needed the cash this month which is a personal question, not a policy one.
Is the ₹1,800 PF cap good news?
The headline reads like a raise. Under the EPF Scheme, 2026, only ₹1,800 a month is compulsory; contributions above the statutory ceiling are voluntary on both sides. Practitioners have been quick to point out that this was substantially the position under the old scheme too; the ceiling was always ₹15,000, and higher contributions always needed agreement. What is new is that the ambiguity is gone, which means it is now an explicit choice someone has to make.
Look at what the choice actually buys at ₹24,00,000 CTC:
| Per year | PF on ceiling | PF on full basic |
|---|---|---|
| Into your EPF account (both sides) | ₹43,200 | ₹2,88,000 |
| Income tax | ₹2,71,877 | ₹2,40,053 |
| Into your bank account | ₹20,27,203 | ₹18,14,227 |
Same CTC, same tax regime, same basic pay. Only the provident fund treatment differs.
You gain ₹2,12,976 in spendable cash and give up ₹2,44,800 of retirement saving. The ₹31,824 that vanishes between those two figures is tax, because provident fund money is sheltered and salary is not. Set against an instrument that has paid in the region of 8.25% tax-free in recent years, and compounds for three decades, that is not an obviously good trade for a 26-year-old. It may be an excellent one for someone clearing an education loan at 11%.
Before you ask payroll to reduce your PF: two constraints apply. Your employer's policy still governs whether a lower deduction is available, since higher contributions require agreement from both sides. And a visible reduction in employer matching is a compensation change, whatever the payslip calls it; if your employer proposes it, treat it as a cut and negotiate accordingly.
Five questions to ask before you sign
Every one of these has a specific, checkable answer. If a recruiter cannot give you one, that itself is information.
- What is the gross monthly salary, and what is the expected monthly credit? Ask for the payslip simulation. Most HR systems generate one in a minute.
- What percentage of the variable component was actually paid out last year, company-wide? Not the target. The paid figure.
- Is provident fund deducted on basic pay or on the ₹15,000 ceiling, and can I elect otherwise? This is the ₹8,400 question from the table above.
- Is the gratuity provision inside my CTC, and what happens to it if I leave at three years? If it is inside CTC and you leave early, you funded a benefit you never received.
- What is the notice period, is buyout permitted, and at gross or basic? Since the 50% rule raised basic, notice-pay buyouts got more expensive for whoever is paying them.
If you are weighing two offers with different structures, our career counselling session includes a side-by-side of what each one actually credits to your account, and our placement desk reviews the offer with you before you sign including the clauses that only matter on the way out.
Frequently asked questions
Is CTC the same as salary?
No. CTC is everything your employer spends on you in a year, including its own provident fund contribution, a gratuity provision, insurance premiums and conditional bonuses. Gross salary is what your payslip shows before deductions. In-hand is what lands in your account after provident fund, professional tax and TDS. All three numbers are different, and only the third one pays rent.
How much in-hand will I get on ₹12 LPA?
About ₹93,995 a month if provident fund is deducted on the ₹15,000 ceiling, or about ₹85,595 if it is deducted on your full basic pay, assuming basic is 50% of CTC and none of the package is variable. Income tax is nil at this level under the new regime, so the entire shortfall from ₹1,00,000 is provident fund and the gratuity provision.
Is PF deduction optional now?
The mandatory employee contribution is 12% of the ₹15,000 statutory wage ceiling, which works out to ₹1,800 a month, and the EPF Scheme, 2026 treats anything above that as voluntary. Whether you can actually lower your own deduction depends on your employer's payroll policy, because contributions above the ceiling need agreement on both sides.
Does the 50% basic salary rule reduce my take-home?
Slightly, yes, and it does not reduce your CTC. A higher basic raises the base for gratuity, leave encashment and notice pay, so more of the same package becomes deferred rather than monthly. The offsetting benefit is that every wage-linked payout you receive later is calculated on a bigger number.
Do I pay income tax on ₹12 LPA in FY 2026-27?
Usually not, under the new regime. The ₹75,000 standard deduction plus the section 87A rebate takes tax to nil where taxable income stays within ₹12,00,000, which covers salary income up to roughly ₹12.75 lakh. Cross that line and tax starts from the first rupee of the slab structure, not from ₹12.75 lakh which is why a ₹13 lakh offer can feel worse than a ₹12.7 lakh one.
Which states deduct professional tax?
It is a state levy, so it varies. Maharashtra, Karnataka, West Bengal, Tamil Nadu, Telangana and Gujarat, among others, deduct up to ₹2,500 a year. Uttar Pradesh, Delhi and Haryana do not levy it. Two identical offers in two cities genuinely credit different amounts.
What this is based on
- Code on Wages, 2019, section 2(y) single definition of wages, with excluded components capped at 50% of total remuneration.
- The four labour codes brought into force on 21 November 2025; Code on Wages (Central) Rules, 2026 and the other central rules notified 8 May 2026.
- Employees' Provident Fund Scheme, 2026, effective 29 June 2026, replacing the 1952 scheme; statutory wage ceiling of ₹15,000 notified 29 May 2026 under the Code on Social Security, 2020.
- Income tax slabs and rates under the new regime for FY 2026-27, standard deduction of ₹75,000 and the rebate under section 87A.
- Code on Social Security, 2020 gratuity, including pro-rata entitlement for fixed-term employees after one year.
Every figure here is illustrative and computed on the stated assumptions: basic at 50% of CTC, gratuity provision at 4.81% of basic, new tax regime, no professional tax and no variable pay. Your own structure will differ. State rules under the labour codes are still being notified and payroll practice is still settling, particularly on provident fund. CareerFluxio is not a tax adviser or a firm of chartered accountants check your own numbers with your employer's payroll team and a qualified professional before acting on them.